
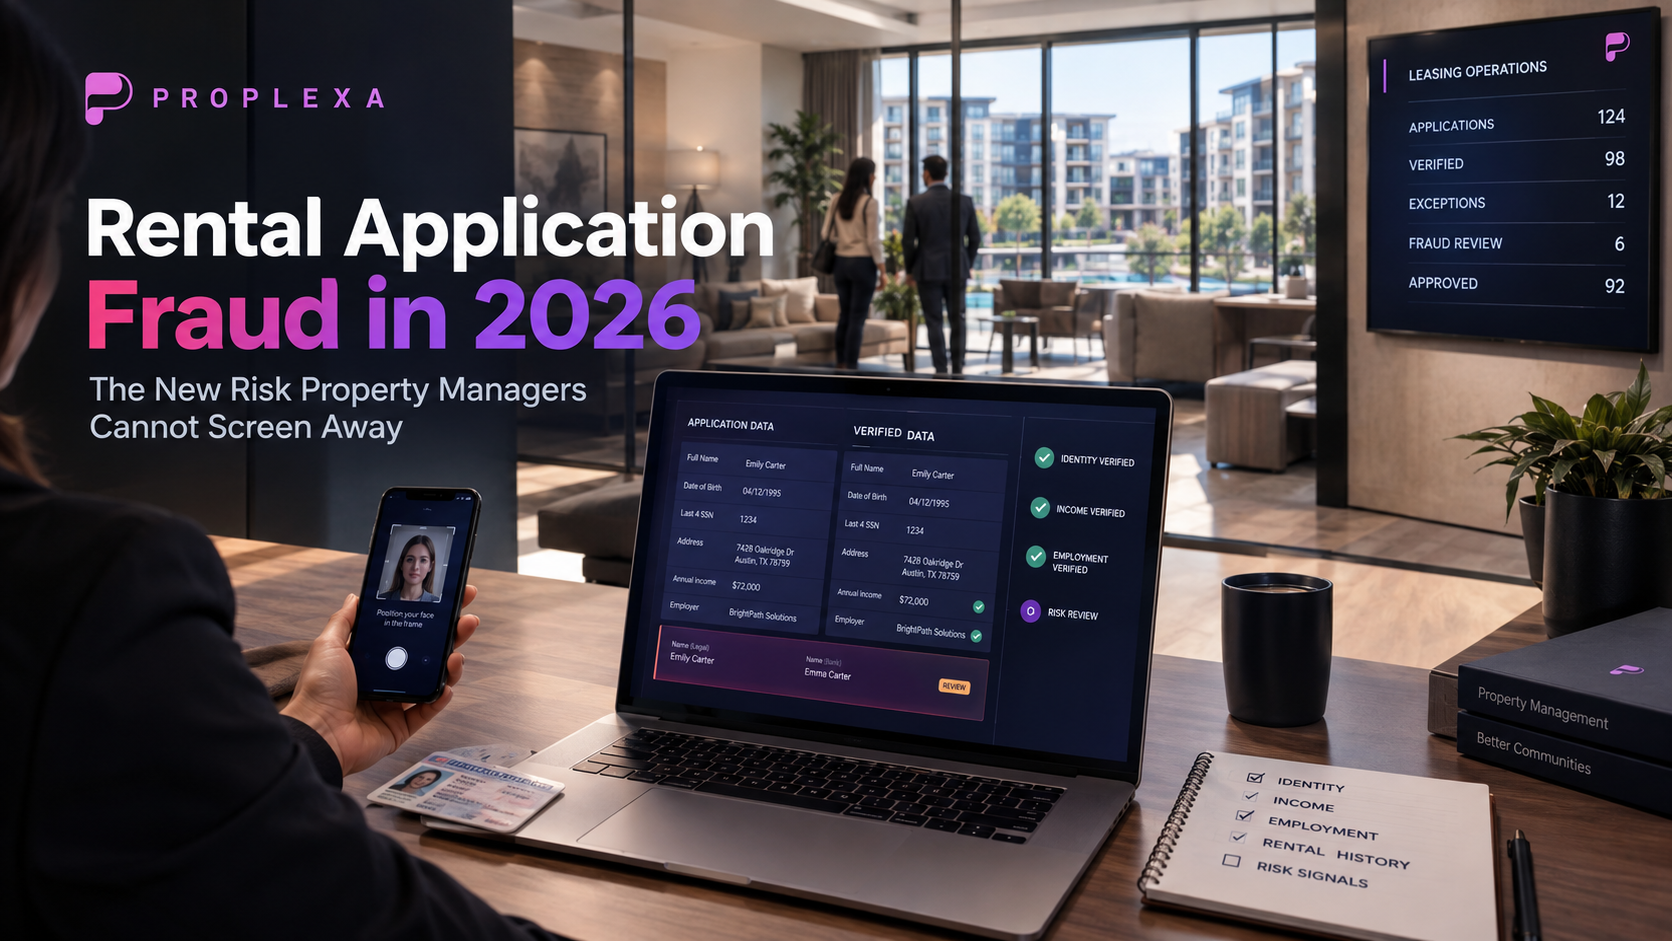
For years, tenant screening was built around a relatively simple assumption:
If the documents look legitimate, the applicant probably is.
That assumption is becoming increasingly difficult to defend.
In 2026, property managers are dealing with falsified income documentation, identity manipulation, concealed eviction histories and applicants whose digital identities may not correspond to the person who ultimately occupies the apartment.
The problem is no longer simply screening.
It is verification.
Fraud Is Becoming a Multifamily Operating Risk
Checkr's 2026 State of Rental Fraud report surveyed 1,400 landlords and property managers across the United States in August 2026.
The findings show how widespread the problem has become:
- 82% are worried about fraud in tenant applications.
- 67% have encountered a fraudulent application.
- 67% say fraud has become harder to detect than one year earlier.
- 46% have lost at least $5,000 from a single fraudulent tenant.
This matters because application fraud does not necessarily end when a lease is signed.
It can become a resident, a delinquency problem, an eviction, legal expense and an extended vacancy.
The Identity Problem Is Bigger Than a Fake Pay Stub
Income-document fraud receives considerable attention, but identity verification creates another layer of risk.
Checkr found that 42% of surveyed landlords and property managers had discovered that the person who moved into a property was not the same person who had applied and been approved. Including respondents who suspected but could not confirm an identity swap, the figure reached 55%.
That creates a fundamentally different problem.
A conventional screening process asks:
“Does this applicant qualify?”
A stronger process also asks:
“Is this actually the person whose information we verified?”
Those are not the same question.
AI Is Raising the Verification Standard
Digital fraud is also becoming more sophisticated.
Checkr reported that 37% of respondents identified fake or altered pay stubs and bank statements as their biggest fraud concern.
Entrata's 2026 State of Multifamily report similarly found that 63% of respondents had seen an increase in fraud over the previous year. Among the fraud categories identified, identity fraud was reported by 95%, income/employment fraud by 67% and payment-method fraud by 61%.
The operational implication is important:
Document review alone is becoming a weaker proxy for applicant verification.
A document can be internally consistent and still be fraudulent.
Credit Data Can Reveal Risk That Documents Miss
Traditional screening should not be abandoned. But property managers can increasingly analyze patterns rather than individual documents.
TransUnion's 2026 analysis identified credit-inquiry velocity as a particularly significant fraud-risk indicator.
Applicants with 15 or more credit inquiries during the seven days before applying showed a 32% charge-off rate within one year, compared with nearly 9% for the overall sample.
This does not mean that a high number of inquiries proves fraud.
It means that behavioral signals can provide additional context that a single credit score or pay stub cannot.
That distinction matters for sophisticated screening.
The Screening Stack Is Changing
A modern multifamily screening process increasingly needs multiple verification layers.
1. Identity Verification
Does the applicant's identity correspond to the information being submitted?
2. Income Verification
Can income be independently validated rather than simply accepted from uploaded documents?
3. Employment Verification
Does the claimed employment information correspond with reliable external data?
4. Credit and Payment History
Does the applicant's financial behavior align with the application?
5. Rental History
Can previous housing information be verified independently?
6. Fraud Signals
Are there anomalies across identity, financial behavior, application activity or documentation?
The objective is not to make screening infinitely complicated.
It is to reduce dependence on one piece of evidence.
Speed vs. Verification Is a False Choice
Leasing teams operate under pressure.
A vacant unit costs money, prospects expect fast responses and applicants increasingly expect digital leasing.
That creates a temptation to optimize for speed alone.
But faster approval is not necessarily better performance if the verification process is weak.
The better objective is:
Fast decisions built on reliable information.
That requires standardized workflows, automated verification where appropriate, exception handling and clear escalation rules.
Technology should reduce manual work without turning screening into an unexamined automated decision.
What Owners Should Ask a Property Manager
When evaluating a PMC, owners should ask questions that reveal the actual screening process:
- How do you verify applicant identity?
- How is income independently verified?
- Which fraud indicators do you monitor?
- How do you detect identity mismatches?
- How are exceptions reviewed?
- How frequently do fraudulent applications reach move-in?
- How do you track fraud-related bad debt?
- Who is responsible for screening decisions?
- How do you document screening procedures?
- How do you maintain Fair Housing compliance?
- How often is your screening technology evaluated?
The objective is not to find a company claiming to have “the best screening.”
It is to understand the controls behind the claim.
Fraud Prevention Is Becoming a Management Capability
This is particularly important for property management companies.
Owners traditionally evaluate PMCs around:
- Leasing
- Collections
- Maintenance
- Accounting
- Resident communication
- Vendor management
Applicant verification belongs in that same operational conversation.
A property manager is effectively controlling access to an owner's asset.
That means the quality of the leasing-control system is part of the manager's operational capability.
Where Proplexa Fits
For Proplexa, this creates an important distinction.
The marketplace should not merely help owners compare:
“Who charges the lowest management fee?”
It can help them compare the operating systems behind the management relationship.
An RFP can ask PMCs to explain:
- Screening methodology
- Identity verification
- Fraud detection
- Leasing technology
- Exception handling
- Compliance procedures
- Reporting
- Collections processes
- Resident onboarding
That creates a more meaningful comparison between management companies.
The question becomes:
How does this PMC protect the owner's asset from operational risk?
The Bottom Line
Rental application fraud is no longer just a screening department problem.
It is an asset-management and operational-risk issue.
In 2026, landlords and property managers are reporting increasingly sophisticated fraud, while new data is showing that identity verification and behavioral signals can reveal risks that conventional document review may miss.
For owners, the takeaway is straightforward:
Do not evaluate a property manager's screening capability by whether they run a background check. Evaluate the verification system behind the background check.
Because in a digital leasing environment, the most expensive applicant may be the one who was never properly verified.